Credit mix is one part of your credit profile: it describes the different kinds of credit accounts you have experience managing. While it can play a role in some credit scores, it works alongside factors such as payment history and the amounts you owe.
Our Credit Mix Mastery checklist offers an affordable way to learn the basics and consider your next steps. Before you apply for another account, start with what you already have and decide what makes sense for your budget.
What Credit Mix Means
Credit accounts generally fall into two broad categories: revolving and installment. Revolving credit lets you borrow against a limit, repay what you owe, and borrow again as available credit is restored. A credit card is a common example. Your balance and required payment can change from month to month.
Installment credit involves borrowing an amount and repaying it over an agreed term, typically through scheduled payments. Auto loans, student loans, and personal loans are examples. The terms, interest charges, and payment amounts depend on the loan.
Common Types of Credit
| Type |
Example |
How it works |
| Revolving |
Credit card |
Borrow up to a limit and repay a changing balance. |
| Installment |
Auto loan |
Repay a set amount over an agreed term. |
Having different account types can help demonstrate experience managing different forms of credit. But a varied mix alone does not guarantee a higher score. Your full credit history matters, and adding a loan you do not need can create obligations that are harder to manage than any potential benefit is worth.
For more detail on how different factors contribute to a FICO Score, see FICO’s explanation of credit score factors.
Start With the Accounts You Have
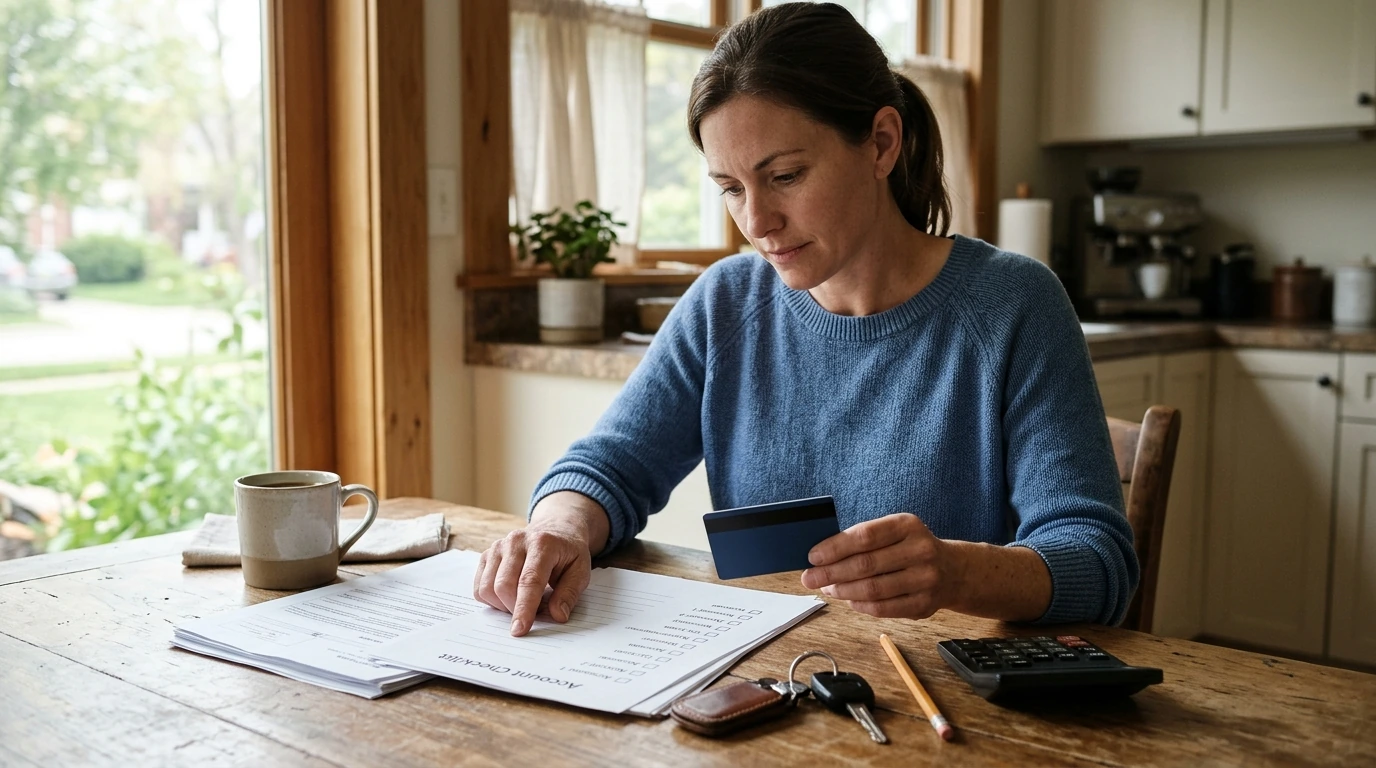
Before considering a new account, review your credit reports and list the account types already reported. You may find that you have both revolving and installment accounts, or that an older account is still part of your reported history. Reviewing the details also gives you a chance to spot an unfamiliar account, an incorrect balance, or a payment marked late in error.
If you find an error, follow the credit bureau’s dispute process and provide supporting information where appropriate. The Consumer Financial Protection Bureau’s credit reports and scores resources can help you understand how to review reports and address inaccuracies.
Next, focus on habits you can maintain:
- Pay on time. Consider reminders or automatic payments that fit your cash flow, and make at least the required payment by the due date.
- Keep card balances manageable. Compare what you owe with your credit limits and choose a repayment plan that fits your budget.
- Review account costs. Interest, annual fees, and other charges can affect whether an account remains useful to you.
Opening an account solely to diversify your mix can add fees or interest and may temporarily affect your score. A credit application can result in a hard inquiry, and a new account can affect the age of your accounts. Consider those tradeoffs before applying.
Use Credit Mix Mastery to Organize Your Next Steps
Our Credit Mix Mastery checklist is a straightforward educational resource for learning how account types fit into a credit profile. At $2.99, it gives you an affordable starting point for organizing your review and thinking through credit decisions.
Use the checklist alongside your existing account information and your financial goals. For example, you might note which accounts you have, identify any report details that need attention, and decide whether your priority is paying down a balance rather than taking on a new payment. If you are considering a necessary purchase that involves financing, compare the total cost and monthly payment with your budget—not just the potential effect on your credit mix.
For a separate approach to building consistent daily habits, our Morning Routine Checklist for a Positive Mindset is another resource you can explore. It is not a credit tool, but it may help you create a routine that leaves time for tasks such as checking payment reminders.
Build Credit Habits That Last
A useful credit plan is one you can follow over time. Check your reports periodically, pay bills on time, and borrow only when the payment and total cost fit your budget. If you have trouble keeping up, contact your lender promptly to discuss available options rather than waiting for the balance to grow.
Credit scoring models differ, and the same action can affect people differently depending on their full credit profiles. Our team offers Credit Mix Mastery for education and organization; the checklist does not promise a score increase. Your next step may be to maintain the accounts you already manage well, rather than add another one.
Before choosing, compare the product details with your daily routine, available space, care needs, and preferred setup. The strongest option is usually the one that fits the intended use clearly and remains simple to clean, store, and check before repeat use.
FAQ
Is credit mix good or bad?
A mix of credit account types can be beneficial, but it is only one part of your credit profile. Taking on unnecessary debt or missing payments can outweigh any potential benefit.
What percentage of your credit score is based on your credit mix?
Credit mix generally accounts for about 10% of a FICO Score. Other credit scoring models may weigh it differently.
Recommended for you





Leave a comment